I’ve taken 3 of my C-Corp clients through IRS audits and we came out the other side with flying colors: the bookkeeping was deemed flawless and there were no changes to the tax return. That said, it’s still an unnerving process and can be a time consuming process. So I’d like to share a few things I’ve learned:
Who does the IRS target for an audit?
I’ve asked the auditors this point blank and they always say that they “randomly select from a pool of tax returns” and that there are “algorithms.” I’m sure there is some scientific method to the madness, but here’s what I’ve noticed. You are more likely to get audited if:
- You have >$5M in Revenue and >$1M in Net Income. If the IRS is going to spend the time auditing you, they need it to be worth their time. So if you are a pre-revenue startup that’s running at a loss, it’s highly unlikely that you’ll be audited. It’s just not worth their time.
- Your corporate address is listed in an affluent neighborhood. Beverly Hills. Atherton. The Hamptons. Alamo/Blackhawk. I think this goes back to point 1; they need to justify the cost of an audit by validating that the stockholders have $$$.
- Well-to-do >20% owners. Shareholders who own more than 20% of the company are listed on Sch. G of the 1120. I wouldn’t be surprised if the IRS cross references past and current personal tax returns to see if the person is well-to-do. If they are, the shareholder could be using the CCorp as a tax loss shelter to offset their other income. (My first point about having revenue and net income is then nullified; the IRS will audit a Corporation that is running at a loss).
If you go under IRS audit, what do the auditors look for?
- Payments made to the executive team!!! This is the #1, biggest thing they will go after. And in particular, the payments that were made outside of the payroll system. The auditors are looking for distributions that were made tax-free, whereas payments made thru a payroll processor like Gusto would’ve already deducted taxes. Let’s say you paid Bob a $7,365 reimbursement for expenses he incurred on his personal card. It could’ve been for travel, AWS, meals, etc. But the IRS doesn’t know that, and to them it looks like you gave Bob a cash bonus. If you don’t have every receipt to back up that reimbursement, you’re in trouble. Yes, they’ll focus on the biggest expenses first and those over $75, but you need receipts. Especially on reimbursements. So for goodness sake…. USE EXPENSIFY!!!
- (Big) Payments made to contractors. Did your company sign a contractor agreement, collect a W9 or W8BEN, and report the vendor’s earnings on a 1099? The auditor is looking to see if your vendors paid their taxes too.
- Validating AR and AP. If you’re reporting on accrual basis and you have a very large AP balance (or low AR balance) at the end of the year, the auditor will reach out to your vendors to see if the balances are real. The rationale here is that the Corporation could be over-reporting AP (inflating expenses) or under-reporting AR (deflating revenue) and hence under reporting their tax liability.
- Sampling random transactions. They’ll ask to see receipts for a small, randomly selected sample of your transactions. It will likely be for big transactions and those over $75.
So What Happens if the IRS Audits Your Tax Return and You Are Missing Receipts?
The IRS auditor is looking for evidence that your claimed business expenses are legitimate deductions. The auditor may ask your CPA to recreate a detailed history of your expenses using bank records and cancelled check. OR, they may remove the expense from your original tax return.
This is all going to depend what the missing items are (and the mood of the auditor, to be honest). If you didn’t save a receipt for your $79 purchase of Google Service Apps, the auditor likely won’t go after this because it’s pretty clearly a business expense. They will go after the 10 x $53 Lululemon purchases because you’re a dude running a tech startup… why are you buying yoga pants?? Auditors will definitely want to see a receipt for the $1,765 you spent on Amazon because it’s unclear as to whether that was for Office Supplies or if it was actually for a cornucopia of doggie chew toys. Luckily this is all these “receipts” are saved in your Amazon account.
Missing receipts during an audit can end up costing you a lot of money, either through CPA fees (to put it all together to prove to the IRS that your expenses were legit), through disallowed deductions that increase your taxable income, through expenses that the IRA agent determines were actually payments to executives (i.e. compensation), or through penalties.
So the best remedy is to keep your receipts! Use an accounting software and expenses management system that capture your receipts. Do your books. If you are a funded startup, you should be using a CPA like Kruze to not only get your tax returns done correctly, but also to get your books ready for tax season (and a possible audit).
Tax Audit 101 for Startups
If your business is audited by the Internal Revenue Service, it’s crucial to be prepared. The IRS audit process can be daunting, but understanding what to expect and having proper documentation can make a significant difference, and working with an experienced CPA can really help you avoid expensive mistakes.
During a tax audit, IRS auditors will examine your business tax return and financial records closely. They’ll look for discrepancies between your reported income and deductions and the supporting documents you provide. Key areas of focus often include:
- Business expenses: Ensure you have receipts and documentation for all claimed business expenses. This includes mileage records, entertainment expenses, office supplies, and any other deductions you’ve claimed.
- Bank statements and credit card statements: These can help verify your business income and expenses. Keep organized records of all business-related transactions.
- Receipts: The IRS may verify receipts for various expenses, especially larger purchases or unusual deductions. If you’re missing receipts, you may be able to use bank account statements or credit card statements as alternative proof.
- Payroll records: The IRS will likely examine payments made to employees and contractors, ensuring proper tax withholding and reporting.
If you’re missing receipts or other documentation, don’t panic. The Cohan rule, based on a tax court decision, allows businesses to claim certain expenses using reasonable estimates. However, it’s always better to have proper documentation, and we strongly recommend that you don’t rely on this rule but instead keep great books!
Remember, creating fake receipts is considered tax fraud and can lead to serious consequences, including criminal penalties. Never do this - it is much better to, and more ethical, to simply admit that you don’t have a receipt vs. counterfeiting one. Work with a tax professional or tax attorney to address any documentation issues honestly.
Respond to Tax Audit Letters Promptly
If you receive an audit letter, don’t ignore it. Respond promptly and consider seeking help from a tax professional who’s experienced with the IRS audit process. They can guide you through the audit, help you gather the necessary documents, and potentially negotiate with the IRS on your behalf.
In case of unfavorable audit findings, you may have options such as appealing the decision or taking the case to tax court. However, these steps should be taken only after careful consideration and consultation with a tax professional.
To minimize the risk of future audits, maintain accurate and organized financial records throughout the year. Use automated payment systems and expense tracking tools to keep better records of your business expenses. This will not only make filing taxes easier but also ensure you’re well-prepared if the IRS does select your business tax return for an audit.
Remember, the tax code requires businesses to maintain records that support their claimed deductions. By keeping organized and detailed financial records, you’ll be in a much stronger position if your business faces an IRS audit.
Hope this helps!
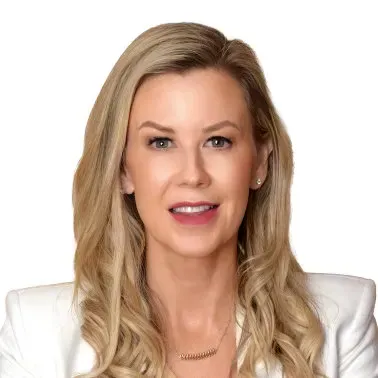
Vanessa Kruze, a seasoned CPA, has an impressive track record prior to establishing Kruze Consulting. Her experience includes pivotal roles at Deloitte Tax and as a controller for a substantial startup with over 120 employees and $20 million in revenue. Under her leadership, Kruze Consulting has emerged as a distinguished CPA firm, recognized on the Inc 5000 list for five consecutive years, illustrating rapid growth and success in the competitive accounting landscape. Vanessa's unique approach, combining deep industry knowledge with advanced automation and software solutions, has positioned her firm as a leader in providing comprehensive accounting services to startups across the United States.
